Life Insurance
LIC New Jeevan Sathi Limited Premium: Complete Guide to Benefits, Premium, Eligibility and Returns
Oct
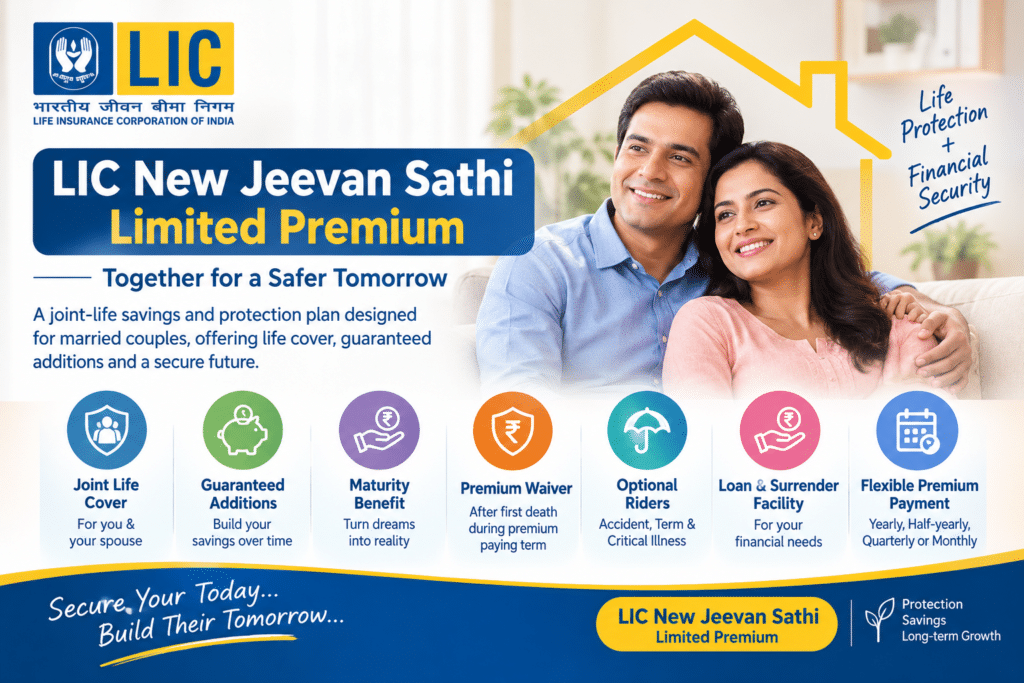
LIC’s New Jeevan Sathi – Limited Premium (UIN: 512N394V01) is a joint-life savings and protection plan designed specifically for a married individual and their spouse. It is a Non-Participating, Non-Linked, Individual Life Insurance Savings Plan that combines life protection with guaranteed additions and maturity benefits.
Unlike participating LIC policies, this plan does not provide bonuses or a share in surplus. Instead, the benefits payable under the policy are guaranteed and fixed according to the terms and conditions of the policy.
The plan allows a married individual to cover themselves as the Primary Life Assured and their spouse as the Secondary Life Assured under one policy. The Primary Life Assured is the policyholder initially; after the death of the Primary Life Assured, the Secondary Life Assured becomes the policyholder.
What Makes LIC New Jeevan Sathi Different?
The biggest attraction of New Jeevan Sathi is that two spouses can be covered under a single joint-life policy.
The plan combines:
- Life insurance protection for both spouses
- Savings for a predetermined period
- Guaranteed Additions
- Premium waiver after the first death during the Premium Paying Term
- Maturity benefit
- Optional insurance riders
- Loan facility
- Surrender facility
- Instalment payment options for death and maturity benefits
The plan also provides flexibility in choosing the Death Benefit Option, Premium Paying Term and Policy Term.
Key Features of LIC New Jeevan Sathi
Here are the major features at a glance:
| Feature | Details |
|---|---|
| Plan type | Non-Par, Non-Linked, Individual Savings Plan |
| Life covered | Primary Life Assured + Spouse |
| Minimum entry age | 18 years for both lives |
| Policy terms | 10, 15, 20 or 25 years |
| Premium Paying Terms | 5, 10 or 15 years |
| Minimum Basic Sum Assured | ₹3 lakh |
| Maximum Basic Sum Assured | No fixed limit, subject to underwriting |
| Basic Sum Assured multiple | ₹10,000 |
| Guaranteed Addition | 7% of Total Tabular Annual Premium, subject to applicable incentives |
| Premium frequency | Yearly, half-yearly, quarterly or monthly |
| Loan | Available subject to conditions |
| Death Benefit Options | Option I and Option II |
The plan also provides incentives for higher Basic Sum Assured, eligible existing LIC policyholders and eligible online purchases.
Who Can Buy LIC New Jeevan Sathi?
The plan is designed for married individuals who want to insure themselves and their spouse under a single policy.
Minimum entry age
The minimum entry age for both lives is:
18 years completed
Maximum entry age
The maximum entry age depends on the selected Death Benefit Option, Premium Paying Term and Policy Term.
For example:
| Premium Paying Term | Policy Term | Option I – Maximum Entry Age | Option II – Maximum Entry Age |
|---|---|---|---|
| 5 years | 10 years | 45 | 40 |
| 5 years | 15 years | 45 | 40 |
| 5 years | 20 years | 45 | 40 |
| 5 years | 25 years | 45 | 35 |
| 10 years | 15 years | 50 | 40 |
| 10 years | 20 years | 50 | 40 |
| 10 years | 25 years | 50 | 35 |
| 15 years | 20 years | 50 | 40 |
| 15 years | 25 years | 50 | 35 |
The minimum maturity age is 28 years.
The maximum maturity age is 75 years for Option I and 60 years for Option II.
The policy term can be 10, 15, 20 or 25 years, while the Premium Paying Term can be 5, 10 or 15 years.
How Much Sum Assured Can You Choose?
The minimum Basic Sum Assured is ₹3 lakh.
There is no stated maximum Basic Sum Assured under the product, although the amount allowed to an individual will be subject to LIC’s Board Approved Underwriting Policy.
The Basic Sum Assured must be selected in multiples of ₹10,000.
Importantly, the risk under the policy begins immediately from the date LIC accepts the risk.
Two Death Benefit Options
One of the most important decisions when purchasing New Jeevan Sathi is choosing between Option I and Option II.
The selected option must be chosen at the proposal stage and cannot subsequently be changed.
Option I
Sum Assured on Death = Higher of:
- 7 × Tabular Annual Premium, or
- Basic Sum Assured
Option II
Sum Assured on Death = Higher of:
- 10.5 × Tabular Annual Premium, or
- Basic Sum Assured
The Tabular Annual Premium is based on the Basic Sum Assured, selected Death Benefit Option and ages of both lives before applicable rebates, loadings, underwriting extras, taxes and rider premiums.
Which option gives higher death cover?
In general, Option II provides the higher premium-based death cover, because it uses 10.5 times the Tabular Annual Premium instead of 7 times under Option I.
However, the premium and benefits vary according to the option selected, so buyers should compare both options before making a decision.
What Happens After the First Death?
This is one of the most important features of the plan.
If one of the two insured spouses dies during the policy term:
- The applicable Sum Assured on Death is paid to the surviving Life Assured.
- The policy continues for the surviving spouse.
- Further base-plan premiums due after the policy anniversary following the first death are waived.
- Rider premiums relating to the surviving Life Assured are not automatically waived and continue according to the rider conditions.
This means the surviving spouse can continue to enjoy the policy’s future benefits without having to pay the remaining base-plan premiums.
What Happens After the Second Death?
If the second Life Assured dies during the policy term, the policy provides:
Sum Assured on Death + Accrued Guaranteed Additions
to the beneficiary or beneficiaries.
The policy then terminates.
The brochure also states that the Death Benefit will not be less than 105% of the Total Premiums Paid up to the date of death, subject to the policy conditions.
What If Both Spouses Die Simultaneously?
If both lives assured die simultaneously during the policy term, the applicable first-death and second-death benefits are payable to the beneficiaries, after which the policy terminates.
The death benefits can be received either as a lump sum or through instalments, depending on the option exercised by the policyholder.
Maturity Benefit
If at least one of the two lives assured survives until the maturity date and the policy is in force, the policy pays:
Basic Sum Assured + Accrued Guaranteed Additions
The brochure defines the Sum Assured on Maturity as equal to the Basic Sum Assured.
This provides a predetermined maturity benefit while also allowing Guaranteed Additions to accumulate during the policy term.
Guaranteed Additions: The Core Savings Feature
For an in-force policy, Guaranteed Additions accrue annually at the rate of:
7% of Total Tabular Annual Premium Paid
The addition is calculated at the end of each policy year during the policy term.
However, eligible incentives can increase the applicable Guaranteed Addition rate.
These incentives may be available for:
- Higher Basic Sum Assured
- Eligible online purchases
- Existing LIC policyholders
- Eligible nominees/beneficiaries of deceased LIC policyholders
For a fully paid-up policy, Guaranteed Additions continue to accrue according to the applicable rules stated in the brochure.
Extra Guaranteed Addition Incentives
LIC provides additional Guaranteed Addition incentives under certain conditions.
1. Higher Basic Sum Assured Incentive
The additional rate depends on the Basic Sum Assured and Policy Term.
| Basic Sum Assured | 10 Years | 15 Years | 20 Years | 25 Years |
|---|---|---|---|---|
| ₹3 lakh to < ₹5 lakh | 0% | 0% | 0% | 0% |
| ₹5 lakh to < ₹10 lakh | 0.15% | 0.15% | 0.20% | 0.40% |
| ₹10 lakh to < ₹15 lakh | 0.30% | 0.30% | 0.45% | 0.80% |
| ₹15 lakh and above | 0.35% | 0.35% | 0.55% | 1.00% |
Therefore, depending on the combination selected, the Guaranteed Addition rate can be higher than the basic 7% rate.
Online Purchase Incentive
Eligible proposals completed through online sales without assistance from an agent or intermediary can receive an additional Guaranteed Addition incentive.
| Premium Paying Term | Additional Rate |
|---|---|
| 5 years | 0.75% |
| 10 years | 0.95% |
| 15 years | 1.25% |
This incentive is provided by increasing the rate of Guaranteed Additions.
Incentive for Existing LIC Policyholders
Existing LIC policyholders and certain eligible nominees or beneficiaries of deceased policyholders can also qualify for additional Guaranteed Additions.
The additional rate is:
| Premium Paying Term | Additional Rate |
|---|---|
| 5 years | 0.05% |
| 10 years | 0.10% |
| 15 years | 0.10% |
Eligibility includes specified circumstances such as an existing LIC policy that has matured within one year before registration of the proposal, certain nominees/beneficiaries of deceased policyholders, or an existing policyholder having an in-force LIC policy.
Optional Riders
The plan offers additional protection through optional riders for an extra premium.
Three riders are mentioned in the brochure:
1. LIC’s Accident Benefit Rider
UIN: 512B203V03
This rider can be opted for during the Premium Paying Term of the base plan, subject to the specified conditions.
In case of accidental death, the Accident Benefit Sum Assured is payable in addition to the death benefit under the base plan.
2. LIC’s New Term Assurance Rider
UIN: 512B210V02
This rider is available at policy inception.
If selected, the Term Rider Sum Assured is payable on the death of the Life Assured during the policy term.
3. LIC’s Critical Illness Health Rider
UIN: 512B227V01
This rider provides two choices:
- Option I: 15 Major Critical Illnesses
- Option II: 40 Major Critical Illnesses, including Assisted Living Benefit
Under Option II, if the Life Assured is diagnosed with one of the specified seven Critical Illnesses, an additional Assisted Living Benefit can provide monthly payouts equal to 1% of the Critical Illness Sum Assured for 36 months.
If the Life Assured dies while receiving these payments, the remaining instalments are paid to the nominee/beneficiary as a lump sum.
The brochure also specifies limits on rider premiums and rider Sum Assured.
Receive Death Benefit in Instalments
Policyholders do not necessarily have to receive the entire Death Benefit as a lump sum.
The plan provides an option to receive the Death Benefit over:
5, 10 or 15 years
The instalments can be paid:
- Monthly
- Quarterly
- Half-yearly
- Yearly
Minimum instalment amounts are:
| Payment Mode | Minimum Instalment |
|---|---|
| Monthly | ₹5,000 |
| Quarterly | ₹15,000 |
| Half-yearly | ₹25,000 |
| Yearly | ₹50,000 |
If the claim amount is insufficient to provide the required minimum instalment, the amount will be paid as a lump sum.
For instalment options commencing from 1 May 2025 to 30 April 2026, the brochure specifies an applicable calculation rate of 4.62% p.a. effective.
Maturity Benefit Can Also Be Taken in Instalments
The policy also provides a Settlement Option for the maturity benefit.
Instead of taking the entire maturity amount at once, the policyholder can choose to receive it over:
- 5 years
- 10 years
- 15 years
Payments can be monthly, quarterly, half-yearly or yearly, subject to the applicable minimum instalment amounts.
For the Settlement Option, the policyholder must exercise the option at least three months before the maturity date.
How Can Premiums Be Paid?
Premiums can be paid:
- Yearly
- Half-yearly
- Quarterly
- Monthly through NACH
- Through salary deductions
The brochure gives the following Premium Conversion Factors:
| Mode | Conversion Factor |
|---|---|
| Yearly | 1.0000 |
| Half-yearly | 0.5090 |
| Quarterly | 0.2568 |
| Monthly | 0.0861 |
The premium for a non-yearly mode is calculated by multiplying the applicable conversion factor by the yearly premium.
Grace Period
If a premium cannot be paid on time, the policy provides a grace period.
Yearly / Half-yearly / Quarterly
30 days
Monthly
15 days
During the grace period, the policy remains in force with risk cover according to the policy terms.
If the premium is not paid before the grace period ends, the policy lapses.
What Happens If You Stop Paying Premiums?
If less than one full year’s premium has been paid and subsequent premiums are not paid, the policy benefits cease after the grace period.
However, after at least one full year’s premium has been paid, the policy can continue as a paid-up policy after the first policy year.
Under a paid-up policy, the Death Benefit and Maturity Benefit are reduced according to the proportion of the Premium Paying Term for which premiums have actually been paid.
The brochure also provides for continued Guaranteed Additions under paid-up conditions according to its specified formula.
Can a Lapsed Policy Be Revived?
Yes.
A lapsed policy can generally be revived during the lifetime of both lives assured within five consecutive years from the First Unpaid Premium, subject to the policy conditions and before the end of the policy term.
Revival requires payment of outstanding premiums along with applicable interest and satisfaction of LIC’s continued insurability requirements.
For the period 1 May 2025 to 30 April 2026, the brochure states the applicable revival interest rate as 9.5% p.a., compounded half-yearly. The basis for determining the rate may change.
Surrender Value
The policy can be surrendered after completion of the first policy year, provided at least one full year’s premium has been paid.
The policy can acquire:
- Guaranteed Surrender Value
- Special Surrender Value
The surrender amount payable is the higher of:
GSV plus applicable surrender value of accrued Guaranteed Additions
or
Special Surrender Value
The Guaranteed Surrender Value depends on the policy term and policy year.
For example, the Guaranteed Surrender Value factor on total premiums paid is 30% in policy year 2 and 35% in policy year 3 across the listed policy terms. It increases according to the applicable policy-year schedule.
The Special Surrender Value is reviewed annually in accordance with the applicable IRDAI requirements.
Important: Surrendering a long-term insurance policy can significantly change the benefits available under the original plan. The applicable surrender value should therefore be checked before surrendering.
Loan Facility
One useful liquidity feature is the policy loan.
A loan can be taken after completion of the first policy year, provided at least one full year’s premium has been paid.
The maximum loan as a percentage of surrender value is:
| Policy Status | Maximum Loan |
|---|---|
| In-force | 75% |
| Paid-up | 50% |
For loans sanctioned during 1 May 2025 to 30 April 2026, the brochure specifies an applicable interest rate of 9.50% p.a., compounded half-yearly.
Loan interest and outstanding loan amounts are subject to the policy conditions and can affect the amount ultimately payable at exit.
Tax Treatment
Applicable statutory taxes are payable by the policyholder according to prevailing tax laws.
The brochure specifically advises policyholders to consult a tax advisor regarding the income-tax benefits or implications associated with premiums and benefits under the plan.
Free-Look Period
If the policyholder is not satisfied with the policy terms and conditions, the policy can be returned to LIC within 30 days from receipt of the electronic or physical policy document, whichever is earlier, stating the reasons for objection.
LIC will refund the premium after deductions permitted under the policy, including applicable risk premium, medical examination expenses and stamp duty charges.
Suicide Exclusion
The brochure contains a specific suicide clause.
If either Life Assured or both lives assured die by suicide within 12 months from commencement of risk or revival, the nominee/beneficiary is entitled to the amount specified under the policy clause, subject to its conditions.
For an in-force policy, this is generally 80% of total premiums paid up to the date of death or the surrender value available on the date of death, whichever is higher, subject to exclusions and the detailed terms of the brochure.
LIC New Jeevan Sathi Premium Example
The brochure provides sample yearly premiums for a ₹3 lakh Basic Sum Assured for standard lives of the same age.
Option I – Offline Sales
| Age | 15-Year Term / 5-Year PPT | 20-Year Term / 10-Year PPT | 25-Year Term / 15-Year PPT |
|---|---|---|---|
| 20 | ₹68,505 | ₹33,045 | ₹20,715 |
| 35 | ₹75,705 | ₹37,035 | ₹25,095 |
| 45 | ₹1,12,470 | ₹50,265 | ₹35,055 |
Option II – Offline Sales
| Age | 15-Year Term / 5-Year PPT | 20-Year Term / 10-Year PPT | 25-Year Term / 15-Year PPT |
|---|---|---|---|
| 20 | ₹71,670 | ₹33,510 | ₹20,715 |
| 25 | ₹72,825 | ₹34,140 | ₹21,330 |
| 35 | ₹84,135 | ₹39,525 | ₹25,095 |
These sample premiums are exclusive of applicable taxes.
Example: Option I Benefit Illustration
The brochure provides an illustration based on:
- Primary Life Assured: 35 years
- Secondary Life Assured: 35 years
- Policy Term: 25 years
- Premium Paying Term: 15 years
- Yearly premium: ₹83,650
- Basic Sum Assured: ₹10 lakh
- Option I
- Offline distribution
Under this illustration, the total annualized premium paid over the 15-year Premium Paying Term is ₹12,54,750.
At the end of 25 years, the illustration shows:
- Guaranteed Additions: ₹17,61,669
- Maturity Benefit: ₹27,61,669
- First Death Benefit: ₹10,00,000
- Second Death Benefit: ₹27,61,669
The illustration is intended to demonstrate the flow of benefits and is based on standard lives and the selected option.
Example: Option II Benefit Illustration
The second illustration uses:
- Primary Life Assured: 35 years
- Secondary Life Assured: 35 years
- Policy Term: 20 years
- Premium Paying Term: 10 years
- Yearly premium: ₹1,31,750
- Basic Sum Assured: ₹10 lakh
- Option II
- Sum Assured on Death at inception: ₹13,83,375
At the end of 20 years, the illustration shows:
- Total annualized premiums: ₹13,17,500
- Guaranteed Additions: ₹15,21,383
- Maturity Benefit: ₹25,21,383
- First Death Benefit: ₹13,83,375
- Second Death Benefit: ₹29,04,758
These figures are from the brochure’s illustration and should not be treated as a personalized quotation. Actual premiums and benefits depend on the applicable policy conditions, ages, underwriting and selected options.
Who May Find This Plan Useful?
LIC New Jeevan Sathi may be relevant for married couples who want:
Joint protection
Both spouses are covered under one policy.
Guaranteed benefits
The product is non-participating, so it does not depend on discretionary bonuses or surplus participation.
Long-term savings
The plan combines insurance protection with a maturity benefit and Guaranteed Additions.
Premium waiver after first death
For the base plan, future premiums are waived after the first death during the Premium Paying Term, subject to the policy conditions.
Additional protection
Optional riders can be added for accident, term insurance and critical illness protection.
Liquidity
The policy provides surrender and loan facilities subject to the applicable conditions.
Important Things to Consider Before Buying
LIC New Jeevan Sathi is a long-term insurance product, so buyers should understand the policy before committing.
1. Choose the Death Benefit Option carefully
Option I and Option II have different premium and death-benefit structures, and the selected option cannot subsequently be changed.
2. Understand the Premium Paying Term
The Premium Paying Term can be 5, 10 or 15 years, while the policy can continue for up to 25 years.
3. Don’t ignore surrender conditions
Early surrender may result in a surrender value that is considerably different from the total premiums paid.
4. Understand paid-up rules
Stopping premiums after the policy acquires paid-up status reduces the applicable Death Benefit and Maturity Benefit.
5. Check rider costs separately
Riders require additional premiums and have their own terms, limits and eligibility conditions.
6. Don’t assume tax benefits
Tax treatment depends on prevailing tax laws. LIC’s brochure advises consulting a tax advisor.
Frequently Asked Questions
What is LIC New Jeevan Sathi Limited Premium?
It is a joint-life, limited-premium, non-participating, non-linked individual savings plan designed to cover a married individual and their spouse under one policy.
Is LIC New Jeevan Sathi a participating policy?
No. It is a Non-Participating plan. Therefore, it does not provide discretionary bonuses or a share in surplus.
What is the minimum Basic Sum Assured?
The minimum Basic Sum Assured is ₹3 lakh.
What are the available policy terms?
The available Policy Terms are 10, 15, 20 and 25 years.
What are the Premium Paying Terms?
You can choose 5, 10 or 15 years.
Can both husband and wife be covered?
Yes. The product is specifically structured as a joint-life plan for a married individual and their spouse.
What happens after the first death?
The applicable Sum Assured on Death is paid to the surviving Life Assured and future base-plan premiums are waived from the policy anniversary following the first death, subject to the conditions.
What happens at maturity?
If at least one Life Assured survives to maturity and the policy is in force, the Basic Sum Assured plus accrued Guaranteed Additions are payable.
Can I take a loan against the policy?
Yes, subject to the loan conditions. The maximum is generally 75% of surrender value for an in-force policy and 50% for a paid-up policy.
Can the maturity benefit be received in instalments?
Yes. The Settlement Option allows the maturity benefit to be received over 5, 10 or 15 years, subject to the applicable conditions.
Final Verdict
LIC’s New Jeevan Sathi – Limited Premium is primarily designed for married couples looking for joint-life protection combined with long-term guaranteed savings.
Its standout features are the single joint-life policy, premium waiver after the first death, Guaranteed Additions, maturity benefit, optional riders, loan facility and instalment options.
The most important decision is selecting the appropriate Death Benefit Option, Policy Term and Premium Paying Term. Buyers should also carefully understand the paid-up, surrender, loan and rider conditions before purchasing.
Most importantly, the figures shown in LIC’s benefit illustrations are examples based on specified assumptions. They should not be interpreted as a personalized quotation or a guarantee that the same premium or benefit will apply to every applicant.
For a purchase decision, prospective policyholders should read the actual policy document and proposal terms carefully and select the option that matches their financial requirements.
